What Is a Personal Loan?
A personal loan is a fixed amount of money you borrow from a bank, credit union or online lender, then repay in equal monthly payments over a set term — most often 12 to 60 months. In Canada, personal loans are usually unsecured: you do not pledge your car or home, and the lender approves you based on income and credit history.
Three features define a standard personal loan:
- Fixed amount. You receive the full sum at once — commonly $500 to $50,000, with $5,000, $10,000 and $20,000 being the most requested sizes.
- Fixed interest rate. Most Canadian personal loans carry a fixed APR, so your payment is identical every month. Variable-rate loans exist but are less common for this product.
- Fixed term. The loan ends on a known date. Unlike a credit card, there is no revolving balance.
Personal Loan Interest Rates in Canada (2026)
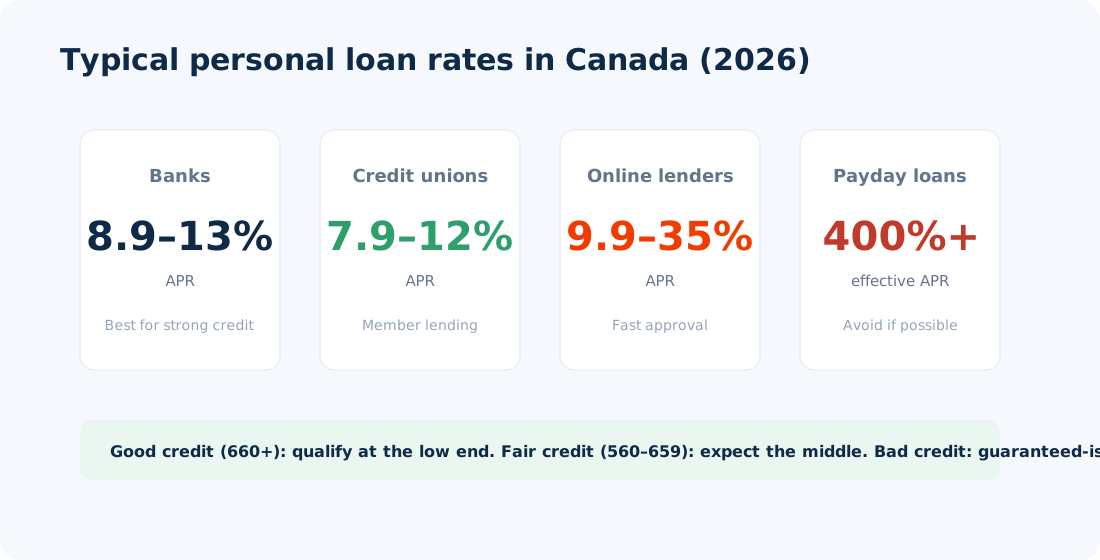
Personal loan interest rates in Canada in 2026 range from about 7.9% APR for strong borrowers at credit unions to 35% APR at online subprime lenders. Provincial caps cap payday products far higher — which is why they should be a last resort.
| Lender type | Typical APR | Loan range | Approval speed | Best for |
|---|---|---|---|---|
| Big banks | 8.9% – 13% | $5,000 – $50,000 | 1–3 business days | Good credit, existing customers |
| Credit unions | 7.9% – 12% | $5,000 – $35,000 | 2–4 business days | Members, often the lowest rate |
| Online lenders | 9.9% – 35% | $500 – $50,000 | Same day – 24h | Fair credit, speed |
| Payday lenders | 390%+ effective | $100 – $1,500 | Minutes | Avoid — last resort only |
What moves your personal loan interest rate
- Credit score. 660+ opens the advertised rates; every 40-point band below adds roughly 1–3 points of APR.
- Debt-to-income ratio. Lenders want total monthly debt payments under 40–44% of gross income.
- Loan term. Shorter terms price lower: a 3-year loan typically beats a 5-year loan by 0.5–1.5 points.
- Employment stability. Two years at the same employer helps; self-employed borrowers need 2 years of tax returns (T1 General).
- Secured vs unsecured. Pledging collateral (a paid-off car, GIC) can cut 2–4 points off the rate.
Personal Loan Calculator
Move the sliders to see the monthly payment and total interest for any personal loan in Canada.
$5,000, $10,000 and $20,000 Personal Loans
Most Canadian borrowers take one of three sizes. Here is what each costs at a representative 10% APR — and what changes at a 20% rate.
$5,000 personal loan
At 10% APR over 3 years: $161/month, $803 total interest. Over 2 years: $231/month, $537 interest. Over 5 years: $106/month, $1,372 interest.
| Term | Payment | Total interest |
|---|---|---|
| 2 years | $231 | $537 |
| 3 years | $161 | $803 |
| 5 years | $106 | $1,372 |
Income needed: roughly $1,600/month gross at the 3-year payment.
$10,000 personal loan
At 10% APR over 3 years: $323/month, $1,616 total interest. Over 5 years: $212/month, $2,728 interest.
| Term | Payment | Total interest |
|---|---|---|
| 3 years | $323 | $1,616 |
| 4 years | $254 | $2,172 |
| 5 years | $212 | $2,728 |
Income needed: roughly $2,900/month gross at the 3-year payment.
$20,000 personal loan
At 10% APR over 3 years: $645/month, $3,231 total interest. At 5 years: $425/month, $5,456 interest. At 7 years: $333/month, $7,963 interest.
| Term | Payment | Total interest |
|---|---|---|
| 3 years | $645 | $3,231 |
| 5 years | $425 | $5,456 |
| 7 years | $333 | $7,963 |
Income needed: roughly $5,200/month gross at the 3-year payment. Banks prefer a credit score of 660+ and stable employment at this size.
Personal Loan from Government in Canada — What Actually Exists
A common search is "personal loan from government Canada". The direct answer: there is no general-purpose personal loan issued by the federal or provincial governments to consumers. What exists instead:
- Canada Student Loans — federal-provincial loans for full- and part-time studies, interest-free during full-time study.
- Provincial emergency and income support — short-term hardship assistance through provincial programs (amounts and rules vary by province).
- Community Futures — small-business loans for rural entrepreneurs, not personal use.
- Indigenous programs — targeted housing and business financing through specific federal programs.
For everyday borrowing — consolidation, repairs, moving — the practical route is a bank, credit union or licensed online lender. Websites advertising "government personal loans" with an application fee are a known scam pattern: no legitimate government program charges an upfront fee for a personal loan.
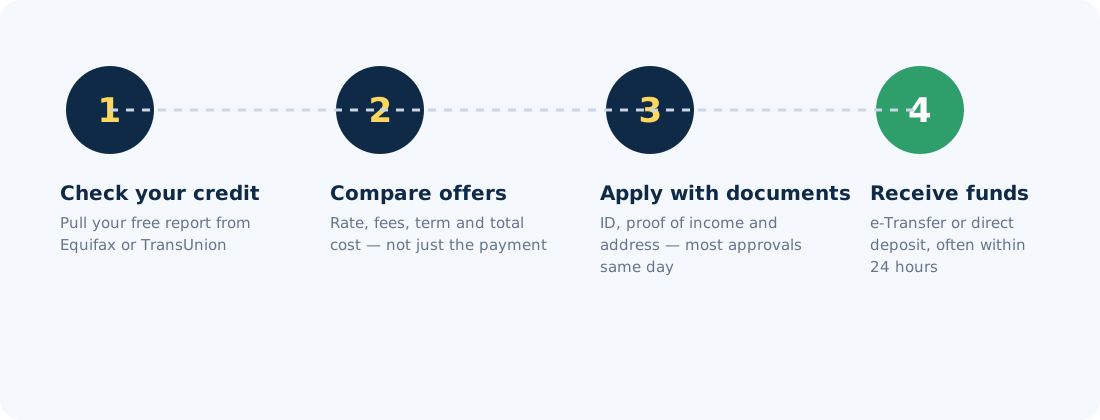
How to Get a Personal Loan in Canada: 4 Steps
Documents to prepare
- Government-issued photo ID (passport, driver's licence)
- Proof of income: two recent pay stubs, or T4/NOA if new to a job
- Proof of address: utility bill or lease
- Bank statements for the last 90 days (online lenders)
Approval checklist
- Credit score 660+ gets standard rates; 560–659 gets subprime pricing
- Debt-to-income under 40% including the new payment
- Income of at least $1,800–$2,000/month gross for most lenders
- No active insolvency (bankruptcy or consumer proposal)
Personal Loan Canada — Most-Searched Questions
What is a personal loan?
A fixed amount borrowed from a bank, credit union or online lender, repaid in equal monthly payments over 12–60 months. Most Canadian personal loans are unsecured and carry a fixed rate, so the payment never changes.
What are personal loan interest rates in Canada in 2026?
Roughly 7.9–13% APR at banks and credit unions for good credit, 9.9–35% at online lenders for fair or bad credit. Your exact rate depends on credit score, income, existing debts and the term you pick.
How do I get the personal loan Canada lowest interest rate?
Fix errors on your credit report first, keep debt-to-income under 40%, compare at least three lenders, take the shortest affordable term, and ask about a co-signer. Credit unions frequently beat bank rates by 0.5–1 point — membership usually requires living in the region or a small share purchase.
How much does a $5,000 personal loan cost per month?
About $161/month at 10% APR over 3 years ($803 total interest), or $186/month at 20% APR ($1,683 interest). Shorter terms cut total cost; the calculator above shows any combination.
How much does a $10,000 personal loan cost per month?
About $323/month at 10% APR over 3 years ($1,616 total interest). Stretching to 5 years drops the payment to $212 but raises interest to $2,728.
How much does a $20,000 personal loan cost per month?
About $645/month at 10% APR over 3 years ($3,231 interest), or $425/month over 5 years ($5,456 interest). Lenders typically want $2,300–$3,300 monthly gross income for approval at this size.
Can I get a personal loan from government in Canada?
No general-purpose government personal loan exists for consumers. Federal programs are targeted: Canada Student Loans for education, provincial emergency support for hardship. Everyday personal loans come from banks, credit unions and licensed online lenders.
What credit score do I need?
660+ for advertised rates at most lenders. 560–659 qualifies at online lenders with higher pricing. Under 560: secured loans, a co-signer, or credit-building products that report to both Equifax and TransUnion.
How fast can I get the money?
Online lenders: same-day approval with Interac e-Transfer funding within 24 hours. Banks and credit unions: 1–3 business days from application to deposit.
Can I pay off my personal loan early?
Most Canadian personal loans have no prepayment penalty — federal rules cap penalties on loans under $250,000. Early payoff saves all remaining interest. Get the no-penalty clause in writing before signing.
Will applying hurt my credit score?
One application causes a hard inquiry worth about 5–10 points, temporary. Rate-shopping within 14 days counts as a single inquiry under most scoring models, so compare freely inside that window.
Is a personal loan better than a credit card?
For fixed expenses and debt consolidation, yes: loan rates beat the 20.99% standard card APR, payments are fixed, and the debt has an end date. For recurring small purchases, a card is more flexible.